Credit Utilization Ratio: What It Is and Why It Matters

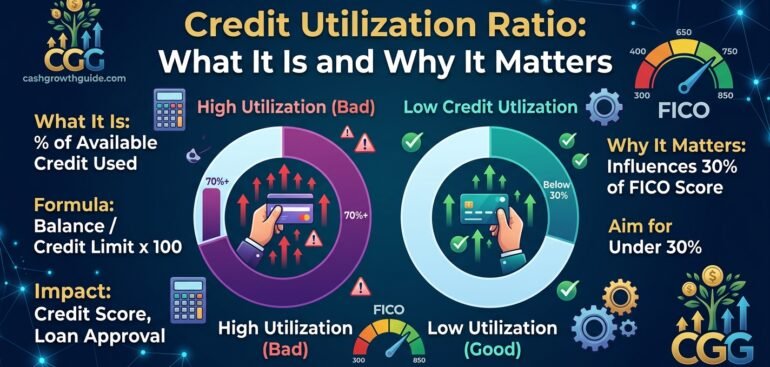
Credit utilization ratio explained with credit limit and balance

Your credit card balance can affect more than your monthly budget. It can also influence how lenders view your credit profile. One of the important measurements to understand is the credit utilization ratio.

Credit utilization shows how much of your available revolving credit you are currently using. If you have credit cards or other revolving accounts, understanding this ratio can help you manage balances more effectively and make informed financial decisions.

A lower utilization level is generally viewed more favorably by many credit scoring models. However, credit utilization is only one part of your overall credit profile. Payment history, credit history, new applications, and other factors can also matter.

At Cash Growth Guide, understanding everyday financial concepts can help you make better money decisions. This guide explains how credit utilization works, how to calculate it, what ideal credit utilization can look like, and how to manage your balances responsibly.

What Is a Credit Utilization Ratio?

The credit utilization ratio measures the percentage of your available revolving credit that you are using.

For example, suppose you have a total credit limit of $5,000 across your credit cards and your current balances add up to $1,000. Your credit utilization would be 20%.

The basic calculation is:

Credit Utilization Ratio = Total Credit Card Balances ÷ Total Credit Limits × 100

This calculation can be considered for an individual credit card as well as across multiple revolving accounts.

For example, if one card has a $2,000 limit and a $400 balance, the utilization for that card is 20%.

The ratio becomes useful because it puts your balance into context. A $500 balance may seem relatively small, but its impact can look different depending on whether your credit limit is $1,000 or $10,000.

Why Does Credit Utilization Matter?

Credit utilization matters because it can be one of the factors considered by credit scoring systems.

A high utilization ratio may indicate that you are relying heavily on available revolving credit. A lower ratio can show that a smaller portion of your available credit is being used.

However, utilization should not be viewed in isolation. A person with low utilization can still have credit problems if they frequently miss payments or have other negative information in their credit history.

Likewise, someone with a temporary increase in utilization may not necessarily have a long-term credit problem.

The goal is to understand the relationship between your credit limits and balances so you can manage your credit more carefully.

How to Calculate Credit Utilization Ratio

Calculating your credit utilization ratio is simple.

First, add together the balances on your revolving credit accounts. Next, add together the credit limits on those accounts. Finally, divide the total balances by the total limits and multiply the result by 100.

For example:

Imagine you have three credit cards:

  • Card A: $500 balance with a $2,000 limit
  • Card B: $700 balance with a $3,000 limit
  • Card C: $300 balance with a $5,000 limit

Your total balance is $1,500.

Your total credit limit is $10,000.

The calculation would be:

$1,500 ÷ $10,000 × 100 = 15%

Your overall credit utilization ratio would therefore be 15%.

This calculation can give you a quick snapshot of how much of your available revolving credit you are using.

What Is Ideal Credit Utilization?

There is no single percentage that guarantees a particular credit score. Credit scoring models can use different calculations and may consider information at different points in time.

Still, keeping utilization relatively low is a common credit-management strategy.

The concept of ideal credit utilization is often discussed because lower utilization may be viewed more positively than very high utilization. The important point is not to treat one percentage as a guaranteed scoring target.

For example, moving from 80% utilization to 30% can represent a meaningful reduction in revolving debt usage. Moving from 30% to 10% may also change the ratio, but the exact effect on a credit score can vary.

Instead of chasing a perfect number, focus on maintaining manageable balances and avoiding unnecessary dependence on available credit.

Individual Credit Card Utilization vs Overall Utilization

There are two utilization measurements you should understand.

The first is individual-card utilization. This looks at the balance and limit of a single credit card.

The second is overall utilization. This looks at your balances and limits across multiple revolving accounts.

For example, imagine you have two cards.

Card A has a $900 balance and a $1,000 limit. Card B has a $100 balance and a $4,000 limit.

Your overall utilization may appear relatively moderate when both cards are considered together. However, Card A itself is using a very high percentage of its available limit.

This is why looking only at your total utilization may not give you the complete picture.

Credit Utilization Calculator: How It Works

A credit utilization calculator can make the calculation faster.

You do not need a complicated formula. You simply need your current revolving balances and corresponding credit limits.

For a single account, enter:

Current Balance: $600
Credit Limit: $2,000

Then calculate:

$600 ÷ $2,000 × 100 = 30%

For multiple accounts, add the balances first and then add the credit limits.

For example:

Total balances: $2,000
Total limits: $10,000

Then:

$2,000 ÷ $10,000 × 100 = 20%

You can also perform the calculation manually using the formula above. The purpose of a credit utilization calculator is simply to make the process quicker and easier.

What Happens When Credit Utilization Is High?

High utilization means you are using a large percentage of your available revolving credit.

For example, if your credit limit is $4,000 and your balance is $3,600, your utilization is 90%.

A high ratio can be a warning sign that your available credit is becoming heavily used. It may also make your monthly payments harder to manage, especially if the balance continues to grow.

High utilization can also become expensive when interest charges accumulate.

The bigger concern is often not the percentage itself but the financial behavior behind it. If you repeatedly need most of your available credit to cover normal expenses, it may be useful to review your budget and spending patterns.

What Happens When Credit Utilization Is Low?

Low utilization means you are using a smaller portion of your available revolving credit.

For example, a $200 balance on a $5,000 credit limit represents 4% utilization.

Low utilization can provide more available credit for unexpected expenses. It can also reduce the risk of reaching your credit limit.

However, low utilization does not automatically mean your overall credit profile is strong.

You still need to pay bills on time, monitor your accounts, manage debt responsibly, and avoid unnecessary credit applications.

Credit management works best when utilization is treated as one part of a broader financial strategy.

Does Paying Your Credit Card in Full Help?

Paying your credit card balance in full can help you avoid carrying revolving debt from month to month and may reduce interest costs.

It can also help keep your balance under control.

However, your reported balance and your payment date are not necessarily the same thing. Credit information can be reported based on account activity at particular points in the billing cycle.

As a result, someone who pays the full balance each month could still have a balance reported at a particular time.

This is why understanding both your spending habits and reporting timing can be useful.

The main objective should be responsible repayment rather than trying to manipulate a particular number.

How to Lower Your Credit Utilization Ratio

If your utilization is higher than you want, there are several practical approaches you can consider.

Pay Down Existing Credit Card Balances

One of the most direct ways to reduce utilization is to reduce your revolving balances.

Start by reviewing the balances on each account. Then create a realistic repayment plan based on your income, essential expenses, and other financial obligations.

Even consistent payments can gradually reduce your outstanding balance.

Avoid Adding New Unnecessary Charges

Paying down a balance becomes harder if you continue adding new purchases to the same account.

Before using a credit card, consider whether the purchase fits within your current budget.

Credit cards can be useful financial tools, but they should not become a substitute for income.

Make Payments Before Balances Become Difficult to Manage

Waiting until a balance becomes very large can make repayment more stressful.

Regular payments can help you maintain better control over your revolving debt.

If your budget allows, you may choose to make payments throughout the billing cycle rather than relying only on one large payment.

Focus on High-Utilization Accounts

If you have several credit cards, identify the accounts that are using the largest percentage of their individual limits.

Reducing a card that is close to its limit can lower that card’s individual utilization.

At the same time, continue monitoring your overall debt so that your repayment strategy remains manageable.

Avoid Unnecessary Credit Limit Increases

A higher credit limit can reduce your utilization ratio if your balance stays unchanged. However, requesting additional credit should not be used as an excuse to spend more.

The important part is controlling the balance.

For example, increasing your limit from $5,000 to $8,000 does not solve a debt problem if your spending increases along with the limit.

Credit availability should support responsible financial management, not encourage additional borrowing.

Does Closing a Credit Card Affect Utilization?

Closing a credit card can change your available credit.

Suppose you have two cards with combined limits of $10,000 and balances of $2,000. Your overall utilization is 20%.

If you close an unused card with a $4,000 limit while keeping the same $2,000 balance, your available credit could fall to $6,000.

Your utilization would then become:

$2,000 ÷ $6,000 × 100 = 33.3%

This example shows why closing an account can change your utilization even when your balance has not changed.

Before closing an account, consider how its credit limit affects your overall profile and whether the account has other financial implications.

Can You Raise Your Credit Score Fast by Lowering Utilization?

People often search for ways to raise credit score fast, especially before applying for financing.

Reducing high credit utilization may help because utilization is one factor that can be considered in credit scoring. However, there is no universal shortcut that guarantees a specific score increase within a specific period.

Your credit score can depend on multiple pieces of information.

If your utilization is very high, paying down balances may improve the credit profile once the lower balances are reflected in the relevant credit information.

Still, it is better to focus on sustainable habits than temporary changes made only to achieve a short-term result.

Does Carrying a Credit Card Balance Improve Your Credit?

Carrying a balance does not automatically make your credit stronger.

You do not need to maintain credit card debt simply to demonstrate credit activity.

In fact, carrying unnecessary balances can result in interest charges and make debt harder to manage.

Responsible credit use is more important than intentionally paying interest. Use credit within your financial means and make payments according to your repayment plan.

Credit Utilization and Your Monthly Budget

Credit utilization is closely connected to budgeting.

If your credit card balance increases every month because your expenses are greater than your available income, lowering utilization may require more than making an occasional payment.

You may need to review your monthly spending.

Start by separating essential expenses from discretionary purchases. Then identify areas where spending can be reduced.

Once your budget becomes more realistic, you can direct additional money toward outstanding credit card balances.

This approach addresses the underlying financial behavior instead of focusing only on the utilization percentage.

How Credit Limits Affect Utilization

Your credit limit directly affects the utilization calculation.

Consider two people with identical $1,000 balances.

Person A has a $2,000 credit limit.

Person B has a $10,000 credit limit.

Person A has 50% utilization, while Person B has 10%.

The balance is exactly the same, but the utilization ratio is different because the available credit is different.

This is why understanding the ratio is more useful than looking at the balance alone.

However, a larger credit limit should never be treated as permission to increase spending.

Common Credit Utilization Mistakes

Many people make avoidable mistakes when managing revolving credit.

One common mistake is looking only at the total balance without considering the credit limit.

Another is assuming that carrying a balance automatically improves credit. It does not.

Some people also close old accounts without considering how the lost credit limit could affect their utilization.

Another mistake is making large purchases simply because enough credit is available.

Finally, some people focus heavily on utilization while ignoring payment history and other important aspects of credit management.

A balanced approach is usually more practical.

How Often Should You Check Your Credit Utilization?

You can check your credit utilization whenever you review your credit card balances and limits.

Monthly monitoring can be especially useful because it fits naturally into a regular financial routine.

You do not need to obsess over daily changes.

Instead, make credit review part of your broader money-management process. Check your balances, review upcoming payments, compare spending with your budget, and identify accounts that may require attention.

A consistent routine can help you spot problems before they become difficult to manage.

A Simple Strategy for Managing Credit Utilization

You can create a simple monthly credit-management routine.

Start by recording the balance and credit limit for each revolving account.

Next, calculate your individual utilization ratios and your overall ratio.

Then review your monthly budget and determine how much you can realistically put toward existing balances.

Avoid unnecessary purchases that could increase revolving debt.

Finally, continue making payments on time and review your progress regularly.

The goal is not to achieve a perfect utilization percentage overnight. The goal is to build habits that keep revolving debt manageable.

Credit Utilization vs Credit Score

Credit utilization and credit score are not the same thing.

Your utilization ratio is a measurement of revolving credit usage. Your credit score is a broader numerical assessment calculated using information from your credit history and other relevant data.

This distinction is important.

A low utilization ratio does not guarantee an excellent credit score. Similarly, a person may have a good credit profile while experiencing temporary changes in utilization.

Think of utilization as one piece of the larger credit picture.

Understanding this difference can prevent unrealistic expectations and help you focus on the financial habits you can control.

Final Thoughts on Credit Utilization Ratio

The credit utilization ratio is an important concept for anyone who uses revolving credit.

It shows how much of your available credit you are using and can help you understand how your balances relate to your credit limits.

Keeping utilization manageable, paying bills on time, avoiding unnecessary debt, and maintaining a realistic budget can all support responsible credit management.

Instead of focusing on a single magic percentage, pay attention to your overall financial behavior. Use a credit utilization calculator when you want a quick calculation, monitor individual and overall utilization, and make repayment decisions that fit your budget.

For more practical personal finance guidance, visit Cash Growth Guide and continue building a stronger understanding of budgeting, saving, debt management, and everyday money decisions.

Frequently Asked Questions

What is a credit utilization ratio?

A credit utilization ratio is the percentage of your available revolving credit that you are currently using. It is calculated by dividing your total revolving credit balances by your total credit limits and multiplying the result by 100.

What is considered ideal credit utilization?

There is no single utilization percentage that guarantees a specific credit score. Lower utilization is generally preferable to very high utilization, but credit scoring also considers other aspects of your credit profile.

How do I calculate my credit utilization?

Add your revolving credit balances, add your credit limits, divide total balances by total limits, and multiply by 100.

For example, $1,000 in balances divided by $5,000 in available credit equals 20% utilization.

Can a credit utilization calculator calculate multiple cards?

Yes. You can use the same basic formula for multiple cards by adding all balances together and all credit limits together before calculating the percentage.

Does high credit utilization hurt your credit score?

High utilization can negatively affect credit scores in some scoring models. The exact impact can vary depending on the scoring model and the rest of your credit profile.

Can I raise my credit score fast by paying down credit cards?

Reducing high revolving balances may help your credit profile once the updated information is reflected. However, there is no guaranteed timeframe or universal amount by which your score will increase.

Does paying my credit card in full help?

Paying the full balance can help you avoid carrying unnecessary revolving debt and interest charges. It can also help you maintain lower balances when managed consistently.

Should I keep a small balance on my credit card?

You do not need to carry a balance simply to build credit. Carrying unnecessary debt can create interest costs and make your finances harder to manage.

Does closing a credit card change utilization?

It can. Closing an account may reduce your total available credit. If your balances remain unchanged, your overall utilization ratio can increase.

Is credit utilization the only credit score factor?

No. Credit scoring can consider several types of information. Payment history, length of credit history, credit accounts, new applications, and other factors may also play a role.

How often should I calculate my credit utilization?

Checking it monthly can be a practical habit. You can calculate it whenever you review your credit card balances, limits, and monthly budget.

Can increasing my credit limit lower utilization?

If your balance remains unchanged, a higher credit limit can mathematically reduce your utilization ratio. However, increasing available credit should not lead to unnecessary spending or additional debt.
15 Practical Ways to Save Money on a Low Income

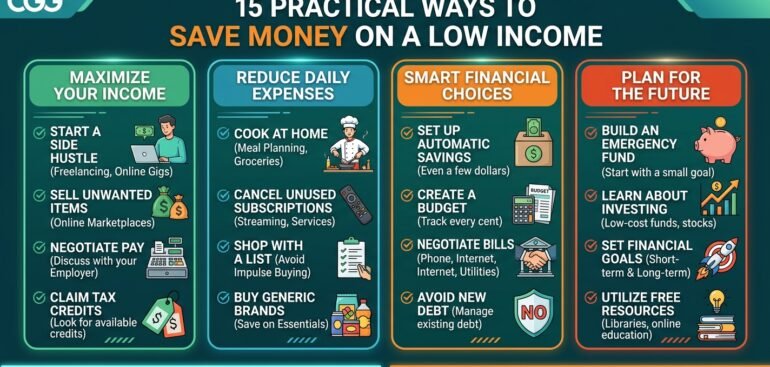
An illustration of five steps for building an emergency fund, featuring various money and banking icons and diagrams. The steps include: Set a Goal, Start Small, Create a Separate Account, Automate Savings, and Track Progress. The illustration has a modern, clean look with a dark background and orange, teal, and blue accents.

Saving money can feel difficult when your income is limited. After paying rent, utilities, groceries, transportation, debt payments, and other necessary expenses, there may seem to be little or nothing left to save.

But having a low income does not mean saving money is impossible.

The key is to focus on realistic changes that fit your current financial situation. You do not need to completely change your lifestyle or save a huge amount every month. Small amounts saved consistently can create a useful financial cushion over time.

Learning how to save money on a low income starts with understanding where your money goes, identifying expenses you can control, and creating a simple system that you can actually maintain.

In this guide, Cash Growth Guide explains 15 practical ways to reduce unnecessary spending, save more from a limited income, and make progress even when you are living paycheck to paycheck.

Why Saving Money on a Low Income Feels Difficult

Before discussing specific strategies, it is important to understand why saving can be challenging when your income is limited.

Many people have fixed expenses that consume a large percentage of their monthly income. Housing, food, transportation, utilities, healthcare, and debt payments are often difficult to reduce quickly.

This means telling someone to “just spend less” is not always helpful.

Instead, the goal should be to identify realistic opportunities to improve your financial situation without creating an unrealistic budget.

You may start by saving a small amount, reducing one unnecessary expense, or finding a way to increase your income.

The most important thing is to make progress without creating a financial plan that you cannot follow.

How to Save Money on a Low Income

There is no single trick that will suddenly create hundreds of dollars in savings.

Instead, saving money usually comes from several small improvements working together.

The following 15 strategies can help you build better money habits and create room for savings.

1. Create a Simple Monthly Budget

The first step in learning how to save money on a low income is understanding exactly where your income goes.

A budget gives your money a purpose before you spend it.

Start by writing down your monthly income and then list your expenses.

Include:

  • Rent or mortgage
  • Utilities
  • Groceries
  • Transportation
  • Insurance
  • Debt payments
  • Healthcare
  • Phone and internet
  • Personal expenses
  • Entertainment
  • Savings

Once everything is written down, compare your total expenses with your income.

This can reveal areas where your spending may be higher than expected.

A budget does not mean you cannot spend money on things you enjoy. It simply helps you decide how much you can realistically afford.

If you need help organizing your monthly finances, Cash Growth Guide provides practical personal finance guidance to help you build a clearer money-management routine.

2. Track Every Expense for 30 Days

If you are not sure where your money is going, track every expense for one month.

Write down even small purchases.

A $3 coffee may not seem important, but repeated small purchases can become a noticeable monthly expense.

Track:

  • Groceries
  • Snacks
  • Transportation
  • Online purchases
  • Subscriptions
  • Dining out
  • Entertainment
  • Personal spending
  • Bills
  • Other purchases

After 30 days, review your spending.

Look for patterns.

You may discover that certain expenses are consuming more money than you realized.

Once you know where your money is going, you can make better decisions about where to reduce spending.

3. Separate Needs From Wants

One of the most useful frugal living tips is learning the difference between needs and wants.

Needs are expenses required for your basic lifestyle and responsibilities.

Examples include:

  • Housing
  • Basic food
  • Essential utilities
  • Necessary transportation
  • Healthcare
  • Required debt payments

Wants are expenses that can improve your lifestyle but are not essential.

Examples include:

  • Restaurant meals
  • Entertainment
  • New clothes when existing clothes are sufficient
  • Premium subscriptions
  • Expensive hobbies
  • Non-essential upgrades

This does not mean you should eliminate every want.

Instead, ask yourself whether a purchase is necessary before spending the money.

If your income is limited, prioritizing needs can create more room for savings.

4. Reduce Grocery Costs

Food is an essential expense, but there may still be ways to reduce your grocery bill.

Start by planning your meals before shopping.

Create a shopping list based on meals you actually intend to prepare.

Avoid buying large quantities of items simply because they appear inexpensive.

You can also:

  • Compare prices
  • Use ingredients across multiple meals
  • Cook larger portions
  • Reduce food waste
  • Use leftovers
  • Buy only what you need
  • Plan meals around ingredients already at home

Small changes in grocery spending can make a meaningful difference over several months.

If you save even $30 each month, that becomes $360 over a year.

5. Cut Unused Subscriptions

Subscriptions can quietly reduce your available income.

Review recurring charges for:

  • Streaming services
  • Apps
  • Fitness memberships
  • Software
  • Online services
  • Subscription boxes
  • Other recurring memberships

Ask yourself how frequently you actually use each service.

If you are paying for something you rarely use, canceling it can create an immediate monthly saving.

You do not need to cancel everything.

Focus on subscriptions that provide little value compared with their cost.

6. Use a “No-Spend” Period

A short no-spend period can help you become more aware of unnecessary purchases.

During a no-spend week, avoid non-essential purchases.

Continue paying for necessary expenses such as housing, utilities, groceries, transportation, and healthcare.

The purpose is not punishment.

It is awareness.

You may discover how often you normally spend money simply because something is convenient or appealing.

After the week ends, identify which purchases you can reduce permanently.

You can repeat a no-spend week occasionally when you need to reset your spending habits.

7. Save Money Automatically

Saving becomes easier when you do not have to make the same decision every month.

If possible, set up an automatic transfer into your savings account after receiving your income.

The amount does not have to be large.

For example:

$25 per month = $300 per year

$50 per month = $600 per year

$100 per month = $1,200 per year

The exact amount depends on your financial situation.

The goal is to create consistency.

Even if you start with $10 or $20, establishing the habit can be more important than the initial amount.

8. Build a Small Emergency Fund

Unexpected expenses can make saving difficult.

A vehicle repair, medical bill, urgent home expense, or temporary loss of income can quickly consume your available money.

This is why building an emergency fund should be one of your financial priorities.

You do not need to start with a huge target.

Begin with a small amount that feels achievable.

For example:

First goal: $100

Then:

$250 → $500 → $1,000 → larger emergency fund

The appropriate long-term target depends on your essential monthly expenses and financial circumstances.

The important thing is to start creating a financial cushion.

9. Reduce Transportation Costs

Transportation can take a significant portion of a limited income.

Review how much you spend on:

  • Fuel
  • Public transportation
  • Parking
  • Vehicle maintenance
  • Insurance
  • Ride services
  • Vehicle payments

Look for realistic ways to reduce these expenses.

Depending on your circumstances, you might combine errands into fewer trips, use public transportation when practical, carpool, walk for short distances, or reduce unnecessary driving.

Even small reductions in transportation costs can create additional money for savings.

10. Cook More Meals at Home

Eating out and ordering food can become expensive when repeated frequently.

Cooking at home gives you more control over your food budget.

You do not need to prepare complicated meals.

Simple meals using affordable ingredients can be enough.

Try planning several meals at the beginning of the week and preparing extra portions for later.

If you normally spend $10 on a meal outside the home several times each week, replacing some of those meals with home-cooked alternatives can create noticeable savings.

You can still enjoy eating out occasionally.

The goal is to make it an intentional expense rather than an automatic habit.

11. Use the 24-Hour Rule Before Buying

Impulse purchases can be particularly harmful when you are trying to save money.

One simple strategy is to wait 24 hours before buying something that is not essential.

Ask yourself:

  • Do I really need it?
  • Do I already own something similar?
  • Can I afford it without affecting my savings?
  • Will I still want it tomorrow?
  • Does it support my current financial goals?

Sometimes the desire disappears after waiting.

If you still want the item after 24 hours and it fits your budget, you can make a more informed decision.

12. Reduce Energy and Utility Costs

Utility bills may not be completely under your control, but small changes can sometimes reduce your monthly costs.

Consider:

  • Turning off unused lights
  • Unplugging devices when appropriate
  • Using energy-efficient lighting
  • Adjusting heating or cooling settings
  • Reducing unnecessary water usage
  • Using appliances efficiently

The savings from individual changes may be small, but recurring savings can add up.

If you save $15 per month, that is $180 over a year.

The goal is to find changes that are easy enough to maintain.

13. Find Ways to Increase Your Income

Saving is only one side of the equation.

When your income is extremely limited, there may be a point where cutting expenses is no longer enough.

Increasing income can give you additional room to save.

Depending on your skills and circumstances, you might consider:

  • Freelance work
  • Part-time work
  • Selling unused items
  • Offering a skill as a service
  • Taking additional shifts
  • Small business opportunities
  • Learning a skill that can improve future earning potential

You do not need to immediately start multiple side jobs.

Even a modest increase in income can help.

For example, an additional $200 per month could potentially be divided between savings, debt payments, and essential expenses.

14. Use Extra Money Strategically

Unexpected or occasional money can provide a useful opportunity to improve your financial situation.

Examples include:

  • Work bonuses
  • Gifts
  • Refunds
  • Extra freelance income
  • Overtime payments
  • Money from selling unused items

You do not have to save all of it.

Instead, consider dividing it according to your priorities.

For example:

50% → Savings

30% → Debt

20% → Personal spending

The exact percentages can change depending on your situation.

The important idea is to avoid allowing unexpected money to disappear entirely through unplanned spending.

15. Create a Paycheck-to-Paycheck Savings Strategy

If you are trying to save money paycheck to paycheck, you may feel that there is no money available for savings.

In that situation, start extremely small.

Instead of saying, “I need to save $500 this month,” start with an amount that you know you can manage.

For example:

  • $5 per paycheck
  • $10 per paycheck
  • $20 per paycheck
  • $25 per paycheck

If you receive two paychecks per month and save $25 from each:

$25 × 2 = $50 per month

Over one year:

$50 × 12 = $600

As your financial situation improves, increase the amount.

The objective is to build a habit that survives even when money is tight.

Frugal Living Tips That Actually Make a Difference

Frugal living does not mean refusing to spend money on everything.

It means being intentional about how you use your resources.

Some practical frugal living tips include:

Buy Based on Value, Not Price Alone

The cheapest product is not always the best financial choice.

Consider how long something will last and whether you actually need it.

Repair When Practical

If something can be repaired affordably instead of replaced, compare the options before purchasing something new.

Use What You Already Own

Before shopping, check whether you already have something that can solve the problem.

Plan Purchases

Planned purchases are usually easier to fit into a budget than spontaneous ones.

Avoid Lifestyle Inflation

When your income increases, you do not have to immediately increase every expense.

Consider directing some of the additional income toward savings or financial goals.

How to Save Money When You Are Living Paycheck to Paycheck

Living paycheck to paycheck can make saving feel impossible.

The first goal should not necessarily be building a massive savings account.

Focus on creating a small buffer.

Start by calculating your essential expenses.

Then identify one expense you can reduce.

Take the amount saved and move it into a separate savings category.

Repeat the process.

For example:

You cancel a $15 subscription.

You reduce restaurant spending by $25.

You save $20 from grocery planning.

You reduce transportation spending by $15.

That creates:

$15 + $25 + $20 + $15 = $75

Instead of looking for one huge expense to eliminate, several small changes can create a meaningful monthly difference.

Create a Weekly Money Check-In

A weekly money check-in can help you stay aware of your finances.

Spend 10 to 15 minutes reviewing:

  • Current account balance
  • Recent purchases
  • Upcoming bills
  • Savings progress
  • Debt payments
  • Spending categories

Ask yourself:

Am I following my plan?

Did an unexpected expense appear?

Can I reduce anything next week?

This simple habit can prevent small problems from becoming larger financial issues.

Give Every Dollar a Purpose

When money is limited, every dollar matters.

Instead of thinking only about how much money you have, think about what that money needs to accomplish.

For example:

  • Housing money pays your rent.
  • Grocery money provides food.
  • Transportation money gets you to work.
  • Savings money builds your financial cushion.
  • Debt money reduces what you owe.
  • Personal spending money gives you controlled flexibility.

Giving your income specific purposes can make it easier to avoid unnecessary spending.

What If You Cannot Save Anything Right Now?

Sometimes your financial situation may genuinely leave no room for savings.

If your essential expenses are higher than your income, the first priority may be stabilizing your monthly finances.

Review your budget carefully.

Look for expenses that can be reduced.

Then consider whether you can increase your income.

Do not feel ashamed if you cannot save a large amount immediately.

Financial progress is not always linear.

Your first goal might simply be to stop increasing debt, reduce one recurring expense, or create a $50 emergency cushion.

Once your financial situation improves, you can increase your savings.

How Much Should You Save on a Low Income?

There is no universal amount that everyone should save.

Your savings target depends on:

  • Income
  • Essential expenses
  • Debt
  • Family responsibilities
  • Financial goals
  • Job stability
  • Existing savings

If your budget is very tight, start with an amount that does not force you to miss essential payments.

For some people, that may be $10 per paycheck.

For others, it may be $50, $100, or more.

Consistency matters.

A small amount saved regularly is better than setting an unrealistic goal that you cannot maintain.

A Simple Low-Income Savings Plan

Here is an example of how someone might organize their finances.

Suppose monthly income is $2,500.

Essential expenses:

  • Housing: $900
  • Utilities: $200
  • Groceries: $350
  • Transportation: $200
  • Insurance: $150
  • Debt payments: $250

Total essential expenses:

$2,050

Remaining:

$450

The person could allocate the remaining amount toward:

  • Emergency savings: $150
  • Future expenses: $100
  • Personal spending: $100
  • Entertainment: $50
  • Miscellaneous: $50

This is only an example.

Your numbers will be different.

The purpose is to show how even a limited income can be divided into clear categories when you create a realistic plan.

Common Mistakes When Trying to Save on a Low Income

Trying to Save Too Much Too Quickly

Setting an extremely aggressive goal may make your budget unsustainable.

Start with an amount you can maintain.

Cutting Everything You Enjoy

A budget with no flexibility can be difficult to follow.

Leave room for reasonable personal spending.

Ignoring Small Expenses

Small purchases can add up.

Track them so you understand their total impact.

Forgetting Irregular Expenses

Annual and occasional expenses can disrupt your savings if you do not plan for them.

Create a category for future expenses.

Giving Up After One Bad Month

Unexpected expenses happen.

If you spend more than planned one month, review what happened and start again.

One difficult month does not erase your progress.

How to Stay Motivated While Saving Money

Saving money can take time, especially when your income is limited.

Instead of focusing only on a large long-term goal, celebrate smaller milestones.

For example:

$100 saved

Then:

$250 saved

Then:

$500 saved

Then:

$1,000 saved

Each milestone represents progress.

You can also track the amount of money you save each month and compare it with previous months.

The goal is not perfection.

The goal is improvement.

Final Thoughts

Learning how to save money on a low income requires patience, realistic planning, and consistency.

You do not need to make dramatic changes overnight.

Start by creating a simple budget and tracking where your money goes. Separate needs from wants, reduce unnecessary recurring expenses, plan your groceries, cook more meals at home, and avoid impulse purchases.

If you are trying to save money paycheck to paycheck, start with a small amount that you can realistically maintain. Even $5 or $10 per paycheck can help you build the habit of saving.

Use these frugal living tips as a starting point, but remember that not every strategy will work for everyone.

Your financial situation is unique.

Choose the changes that fit your income, responsibilities, and lifestyle.

Most importantly, do not measure your progress only by the size of your savings account. Better financial habits, lower unnecessary spending, and greater awareness of your money are also meaningful forms of progress.

Cash Growth Guide is focused on helping you understand practical personal finance strategies so you can make more informed decisions about your money.

Start small, stay consistent, and improve your financial system one step at a time.

Frequently Asked Questions

How can I save money on a low income?

Start by creating a realistic budget, tracking your expenses, reducing unnecessary spending, and saving a small amount consistently. You can also look for ways to reduce recurring expenses or increase your income.

What is the easiest way to save money on a low income?

The easiest starting point is to choose a small savings amount that you can maintain every payday. Automating that amount can make saving more consistent.

How much should I save from each paycheck?

There is no universal amount. Choose a figure that fits your budget after essential expenses and required payments. Even a small amount can help establish a regular savings habit.

How can I save money when I live paycheck to paycheck?

Start with a very small amount and look for manageable expense reductions. Track your spending, reduce unnecessary recurring costs, plan meals, and direct some extra income toward savings whenever possible.

What are the best frugal living tips for beginners?

Useful frugal living tips include meal planning, reducing unused subscriptions, avoiding impulse purchases, using what you already own, comparing costs, and planning purchases before spending.

Is it possible to save money with a very low income?

Yes, although the amount you can save may be small. The important thing is to focus on realistic savings, reduce unnecessary expenses where possible, and consider ways to increase income when expense reductions are not enough.

Should I pay debt or save money first?

Your priorities depend on your financial circumstances. It can be useful to maintain a small emergency cushion while continuing to make required debt payments. From there, you can decide how to divide additional money between savings and debt reduction.

How can I stop spending money unnecessarily?

Start by tracking your purchases and identifying triggers for unnecessary spending. Waiting before non-essential purchases, creating spending limits, and separating needs from wants can help.

How can I reduce my grocery bill?

Plan meals, create a shopping list, use ingredients efficiently, reduce food waste, cook at home, and avoid buying items you do not actually need.

How can I save money without feeling deprived?

Create a realistic budget that includes some money for entertainment and personal spending. The goal is not to eliminate everything enjoyable but to make those expenses intentional and affordable.

What should I do if I cannot save anything?

Review your essential expenses and look for areas where costs can be reduced. If your income still does not cover your needs, consider ways to increase income. Once your financial situation improves, begin with a small savings target.

How long does it take to build savings on a low income?

It depends on your income, expenses, and monthly savings amount. Even small contributions can build over time. Focus on consistency rather than expecting immediate results.

Should I save a fixed amount every month?

A fixed amount can make saving easier to maintain if your income is stable. If your income changes, you can adjust the amount based on what you can realistically afford.

Can small savings really make a difference?

Yes. Small monthly savings accumulate over time. For example, saving $50 per month adds up to $600 over one year, before considering any additional growth.

What is the most important step when learning how to save money on a low income?

The most important step is to understand your current financial situation. Once you know your income, essential expenses, and spending habits, you can identify realistic opportunities to save and create a plan that you can actually follow.

Zero-Based Budgeting: What It Is and How to Start This Month

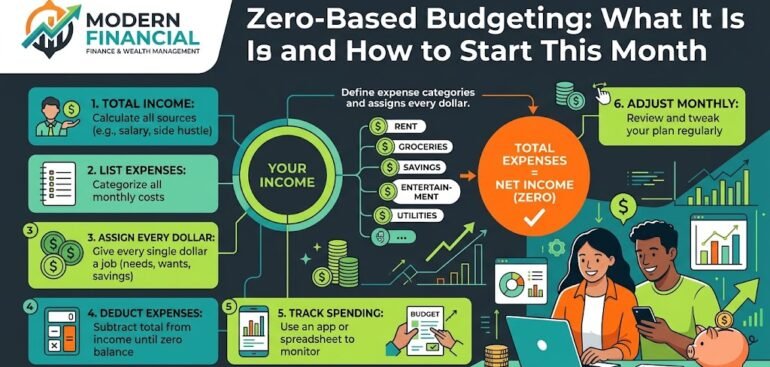
Zero-based budgeting infographic showing step by step process of allocating income minus expenses to equal zero with financial icons.

Zero based budgeting offers a different approach. Instead of spending first and reviewing your finances later, you create a plan before the money disappears. Every dollar of your income is assigned to a specific purpose, such as housing, groceries, transportation, savings, debt payments, or personal spending.

Managing money becomes much easier when you know exactly what every dollar is supposed to do. Many people receive their income, pay a few bills, spend on everyday needs, and then wonder where the rest of their money went. Even when income is enough to cover expenses, unplanned spending can make it difficult to save or reach financial goals.

The goal is simple: your income minus all planned allocations should equal zero.

That does not mean you have to spend every dollar. Money assigned to savings, an emergency fund, or debt repayment still has a job. The idea is to make sure there is no money sitting unplanned.

In this beginner-friendly guide, Cash Growth Guide explains what zero-based budgeting is, how it works, how to create your first budget this month, and how to use a zero based budget example to understand the method.

What Is Zero-Based Budgeting?

Zero based budgeting is a budgeting method where you assign your entire income to specific categories until the amount left to assign reaches zero.

The basic formula is:

Monthly Income – Planned Allocations = $0

The important word is “allocations.”

A zero-based budget does not mean your bank account should reach zero. Instead, it means every dollar has already been given a purpose.

For example, imagine you receive $3,000 this month. You could assign that money to:

  • Housing
  • Utilities
  • Groceries
  • Transportation
  • Insurance
  • Debt payments
  • Savings
  • Emergency fund
  • Entertainment
  • Personal spending
  • Future expenses

If all of these categories together equal $3,000, your budget is zero-based.

There is no unassigned money left.

This approach follows a simple principle: give every dollar a job.

When money has a job before you spend it, you are less likely to spend it simply because it happens to be available in your account.

What Does “Give Every Dollar a Job” Mean?

The idea behind give every dollar a job is straightforward: every dollar you receive should have a purpose.

Suppose you earn $3,000 and your regular expenses total $2,600. You might normally think you have $400 available to spend.

With zero-based budgeting, you decide what that $400 should do before you spend it.

You could assign:

  • $150 to your emergency fund
  • $100 to debt repayment
  • $75 to a future purchase
  • $50 to entertainment
  • $25 to miscellaneous expenses

Now the entire $3,000 has been assigned.

The $400 did not disappear into random spending. Every part of it received a specific job.

This approach can help you become more intentional with money because you make spending decisions in advance rather than making them impulsively.

How Is Zero-Based Budgeting Different From a Traditional Budget?

A traditional budget may tell you how much you expect to spend in several broad categories.

For example, you might decide to spend:

  • $1,000 on housing
  • $400 on groceries
  • $200 on transportation
  • $300 on savings
  • $200 on entertainment

But there may still be money left over without a specific purpose.

Zero-based budgeting takes the process further.

Instead of leaving money unassigned, you continue allocating it until every dollar has a job.

The difference is not necessarily how much you earn or spend. The difference is how deliberately you plan the money you already have.

A traditional budget may help you track spending.

A zero-based budget is designed to help you decide where your money should go before you spend it.

Why Does Zero-Based Budgeting Work?

The biggest advantage of zero based budgeting is awareness.

When every dollar is assigned, you have a clearer picture of your financial priorities.

You know what money is available for groceries.

You know how much is reserved for bills.

You know how much is going toward savings.

You know how much can be used for flexible spending.

This can reduce the uncertainty that often comes with managing money.

It Helps Control Unplanned Spending

Unplanned spending can happen when money appears to be available.

If your bank account shows $700, you may feel comfortable spending $100 on something you want. But that $700 may actually need to cover groceries, utilities, transportation, and upcoming bills.

A zero-based budget gives those dollars specific jobs.

Instead of seeing $700 as available money, you see it as money already assigned to different responsibilities.

It Makes Savings More Intentional

Saving whatever remains at the end of the month can be difficult.

If savings is not included in your plan, other expenses can easily consume the available money.

Zero-based budgeting allows you to assign money to savings before discretionary spending takes over.

It Helps With Debt Repayment

Debt payments can also receive a specific job in your budget.

You can include required payments as well as additional payments when your finances allow.

This makes debt reduction part of your overall financial plan rather than something you handle only when extra money happens to be available.

How to Start Zero-Based Budgeting This Month

Starting a new budgeting system does not need to be complicated.

You can create your first zero-based budget using the following steps.

Step 1: Calculate Your Monthly Income

Start by determining how much money you expect to have available during the month.

If your income is fixed, this may be easy.

If your income changes, use a conservative estimate based on what you can reasonably expect.

Include reliable sources such as:

  • Salary
  • Freelance income
  • Business income
  • Part-time income
  • Commissions
  • Other predictable income

Use your take-home income rather than an amount you will not actually receive.

The goal is to build your budget around money that is genuinely available.

Step 2: List Your Fixed Expenses

Next, write down expenses that are relatively predictable.

These may include:

  • Rent or mortgage
  • Insurance
  • Loan payments
  • Phone bills
  • Internet
  • Subscription services
  • School or education payments
  • Other recurring bills

Fixed expenses should be included before flexible spending because they usually have specific due dates and requirements.

Step 3: List Your Variable Expenses

Variable expenses can change from month to month.

Examples include:

  • Groceries
  • Electricity
  • Fuel
  • Transportation
  • Dining out
  • Entertainment
  • Shopping
  • Personal care
  • Household items

Review your previous spending if possible.

This gives you a more realistic starting point than simply guessing how much you spend.

Step 4: Add Savings Goals

Savings should be treated as an actual category.

You might create separate categories for:

  • Emergency savings
  • Short-term savings
  • Future purchases
  • Education
  • Travel
  • Retirement
  • Other financial goals

The amount you save will depend on your income, expenses, debt, and priorities.

The key is to assign an amount that is realistic enough to maintain consistently.

Step 5: Include Debt Payments

If you have debt, include it in your zero-based budget.

Start with required payments.

Then determine whether you can allocate additional money toward debt reduction.

For example, if your required debt payments are $250 and you decide to make an additional $100 payment, your budget should reflect the full $350 allocation.

This gives your debt a clear place in your financial plan.

Step 6: Plan for Irregular Expenses

Some expenses do not happen every month.

Examples include:

  • Annual insurance
  • Vehicle maintenance
  • Gifts
  • School expenses
  • Home repairs
  • Medical costs
  • Seasonal expenses
  • Annual memberships

These expenses can cause problems when they are ignored.

Instead, estimate the annual cost and divide it into monthly amounts.

For example, if you expect to spend $600 on a particular annual expense:

$600 ÷ 12 = $50 per month

You can then assign $50 each month toward that future expense.

This makes large occasional costs easier to manage.

Step 7: Add Flexible Spending

A zero-based budget does not mean you cannot enjoy your money.

You can create categories for things you enjoy, such as:

  • Dining out
  • Entertainment
  • Hobbies
  • Shopping
  • Personal spending
  • Social activities

The purpose is not to eliminate fun.

The purpose is to decide how much you can comfortably spend without interfering with your important financial responsibilities.

Step 8: Assign Every Dollar

Now comes the most important step.

Take your total monthly income and start assigning it to your categories.

For example:

Income: $3,500

You might assign:

  • Housing: $1,000
  • Utilities: $250
  • Groceries: $450
  • Transportation: $250
  • Insurance: $200
  • Debt: $300
  • Savings: $400
  • Personal spending: $200
  • Entertainment: $150
  • Future expenses: $150
  • Miscellaneous: $150

Total allocations:

$3,500

Money remaining to assign:

$0

That is a zero-based budget.

Zero Based Budget Example

A practical zero based budget example can make the concept easier to understand.

Imagine a person earns $4,000 per month after taxes.

Their monthly plan could look like this:

CategoryPlanned Amount
Housing$1,200
Utilities$250
Groceries$450
Transportation$250
Insurance$200
Debt Payments$300
Emergency Fund$400
Long-Term Savings$300
Personal Spending$200
Entertainment$150
Irregular Expenses$150
Miscellaneous$150
Total$4,000

In this example, the full $4,000 has been assigned.

There is no money left without a purpose.

Notice that savings and debt payments are included in the allocations. This is why zero-based budgeting does not mean spending everything.

Some money is being spent, some is being saved, and some is being used to improve the person’s financial position.

What If You Have Money Left Over?

If you finish your initial budget and still have money left over, do not automatically spend it.

Ask yourself what that money could accomplish.

You could assign it toward:

  • Emergency savings
  • Debt repayment
  • A future purchase
  • Retirement savings
  • Annual expenses
  • A financial goal
  • A reasonable amount of personal spending

For example, if your income is $3,500 and your initial allocations total $3,300, you still have $200 to assign.

You could divide it between savings and debt repayment.

The goal is not to find ways to spend the remaining money.

The goal is to give it a meaningful purpose.

What If Your Budget Is More Than Your Income?

This is where budgeting becomes especially useful.

Suppose your monthly income is $3,000 but your planned expenses total $3,400.

You have a $400 gap.

Instead of ignoring it, review your categories.

Start by looking at flexible expenses.

Could you reduce:

  • Dining out?
  • Entertainment?
  • Shopping?
  • Subscriptions?
  • Personal spending?
  • Non-essential purchases?

If your essential expenses are already very high, cutting small expenses may not be enough.

In that situation, you may also need to consider ways to increase income or reduce larger recurring costs.

The purpose of zero-based budgeting is to make the problem visible so you can make informed decisions.

How to Handle Unexpected Expenses

Even a carefully planned budget cannot predict everything.

Your car may need a repair.

A medical expense may appear.

A household item may need to be replaced.

When an unexpected expense occurs, do not assume your entire budget has failed.

Instead, adjust your allocations.

For example, suppose you have $150 available in your entertainment category but need $100 for an unexpected repair.

You could move $100 from entertainment toward the repair.

Now the repair has been funded without increasing your total budget.

This flexibility is important.

A zero-based budget is a plan, not a prison.

Zero-Based Budgeting With Irregular Income

People with variable income may find budgeting more challenging because the exact amount available can change each month.

If your income is inconsistent, avoid building your plan around your best month.

Instead, use a realistic conservative estimate.

For example, if your monthly income usually ranges between $2,500 and $3,500, you might create your essential plan around the lower end.

When you earn more than expected, you can assign the additional money toward:

  • Emergency savings
  • Debt repayment
  • Future expenses
  • Long-term goals
  • Other priorities

This approach can make variable income easier to manage because you are not depending on an unusually strong month to cover essential expenses.

How to Make Zero-Based Budgeting Easier

A budgeting system should help your financial life, not make it unnecessarily stressful.

Here are several ways to make the process easier.

Keep Your Categories Simple

You do not need dozens of categories when you are starting.

Begin with major areas such as:

  • Housing
  • Utilities
  • Food
  • Transportation
  • Debt
  • Savings
  • Personal spending
  • Entertainment
  • Miscellaneous

You can create additional categories later if needed.

Review Your Budget Weekly

Do not wait until the end of the month to see whether your plan worked.

Spend a few minutes each week reviewing your spending.

Ask:

  • How much have I spent?
  • Which categories are getting close to their limits?
  • Do I need to adjust anything?
  • Are upcoming expenses properly funded?

Regular reviews make it easier to make small adjustments before they become larger problems.

Give Savings a Specific Purpose

Instead of having one general savings category, you can create separate goals.

For example:

Emergency Fund: $200

Future Purchase: $100

Annual Expenses: $100

Specific goals can make saving feel more meaningful.

Leave Room for Real Life

A budget that has no flexibility can be difficult to maintain.

Include a reasonable miscellaneous category for expenses that do not fit neatly into your other categories.

This can help prevent one unexpected purchase from disrupting the entire month.

Common Zero-Based Budgeting Mistakes

Even a simple system can become difficult if you make a few common mistakes.

Mistake 1: Thinking Zero Means Spend Everything

Zero does not mean an empty bank account.

It means zero money remains unassigned.

Savings and debt payments are both valid jobs for your money.

Mistake 2: Forgetting Irregular Expenses

Annual and seasonal expenses should not be ignored.

Plan for them before they arrive.

Mistake 3: Making the Budget Too Strict

If your budget does not allow any reasonable personal spending, you may find it difficult to maintain.

Build flexibility into your plan.

Mistake 4: Using Unrealistic Numbers

If you normally spend $400 on groceries, setting a $150 grocery limit without a realistic plan for reducing costs may cause frustration.

Use actual spending data as your starting point.

Mistake 5: Never Adjusting the Budget

Your budget should change when your circumstances change.

Income may increase or decrease.

Bills may change.

Financial goals may change.

Adjust your allocations when necessary.

Is Zero-Based Budgeting Right for You?

Zero based budgeting can be especially useful if you want greater control over your money.

It may be a good fit if:

  • You frequently wonder where your money went.
  • You want to increase savings.
  • You are working toward debt reduction.
  • Your spending needs more structure.
  • You want every dollar to have a clear purpose.
  • You are working toward specific financial goals.

However, you do not have to make your budget extremely detailed.

If a simpler system helps you stay consistent, start there and gradually add more detail.

The best budgeting method is one you can actually maintain.

How to Start Your Zero-Based Budget Today

You do not need to wait until the beginning of next year or even the beginning of next month.

You can start today.

Write down your expected income.

Then list your essential expenses.

Add debt payments.

Add savings goals.

Add flexible spending.

Plan for irregular expenses.

Finally, assign every remaining dollar until the amount left to assign reaches zero.

Your first budget may not be perfect.

That is okay.

The first month is an opportunity to learn how your money actually behaves.

After reviewing your spending, you can make better decisions for the following month.

Zero-Based Budgeting vs. Simply Tracking Expenses

Tracking expenses tells you what happened.

Zero-based budgeting helps you decide what should happen.

For example, expense tracking might show that you spent $500 on dining out last month.

A zero-based budget allows you to decide before the month starts that dining out will have a $200 allocation.

This creates a spending boundary before the money is gone.

Tracking is still useful, but planning gives your spending more direction.

Using both together can create a stronger financial routine.

Build a Budget That Supports Your Goals

The purpose of budgeting is not simply to create restrictions.

Your budget should support the life you want to build.

If your goal is financial security, your budget can prioritize emergency savings.

If your goal is debt reduction, you can assign more money toward debt.

If you are saving for a major purchase, you can create a dedicated category.

If you want more freedom with your money, you can intentionally create flexible spending categories.

Every dollar should support something that matters to you.

That is the real power behind the principle give every dollar a job.

Frequently Asked Questions

What is zero-based budgeting?

Zero-based budgeting is a method where you assign all of your monthly income to specific categories until the amount left to assign reaches zero. The money can go toward bills, savings, debt payments, future expenses, or personal spending.

Does zero-based budgeting mean spending all your money?

No. Zero-based budgeting does not mean your bank account should reach zero. It means every dollar has been assigned a purpose. Money allocated to savings or debt repayment has a job even though it has not been spent.

What does “give every dollar a job” mean?

“Give every dollar a job” means deciding what each dollar of your income should accomplish before you spend it. A dollar might pay a bill, buy groceries, build savings, reduce debt, or fund a future expense.

How do I start zero-based budgeting?

Start by calculating your monthly income, listing your expenses, adding savings and debt goals, planning for irregular expenses, and assigning the remaining money to specific categories until your amount left to assign reaches zero.

Can zero-based budgeting work with irregular income?

Yes. If your income changes from month to month, use a conservative estimate for essential planning. When you receive more income than expected, assign the additional money to savings, debt, future expenses, or other financial priorities.

What is a zero based budget example?

A zero based budget example could be a person earning $4,000 and assigning the full amount to housing, utilities, groceries, transportation, debt payments, savings, personal spending, entertainment, and future expenses. When all allocations total $4,000, the amount left to assign is zero.

Is zero-based budgeting difficult for beginners?

It may take some time to get used to because you need to think about each category. However, beginners can start with a small number of categories and make the system more detailed over time.

What should I do if I overspend in one category?

Review your remaining categories and move money from a lower-priority category if possible. For example, if groceries cost more than expected, you might temporarily reduce entertainment or another flexible category.

Should savings be included in zero-based budgeting?

Yes. Savings should be treated as one of your planned allocations. You can create categories for emergency savings, future purchases, annual expenses, retirement, or other financial goals.

Can I change my zero-based budget during the month?

Yes. Your budget should be flexible enough to respond to real-life changes. If one category needs more money, you can move funds from another category as long as your overall plan remains balanced.

Final Thoughts

Zero based budgeting gives you a simple but powerful way to take control of your money. Instead of allowing income to disappear through unplanned spending, you decide where your money should go before the month gets busy.

The basic process is straightforward: calculate your income, list your expenses, plan for savings and debt, prepare for irregular costs, and assign every dollar until nothing remains unassigned.

Remember that zero-based budgeting does not mean spending everything. It means making sure every dollar has a purpose.

Your first budget does not have to be perfect. Start with realistic numbers, track your actual spending, review your progress, and make adjustments as you learn more about your financial habits.

At Cash Growth Guide, the goal is to make personal finance easier to understand and easier to apply. A practical budget can help you make better decisions today while creating a stronger foundation for your future financial goals.